April 24, 2020

How Longtime Menke client Hansen Plastics Transitioned to Employee Ownership

At our October 2019 board meeting the younger board members expressed a desire to hear the story of why and how I chose to transition company ownership from me, a sole stockholder, to an “ESOP.” Here is my brief explanation.

We started HPC in 1971 on a shoestring, with a used 40 ton molding press, purchased with $8,000.00 of borrowed money. How we grew the company for the next 27 years will be told in another story.
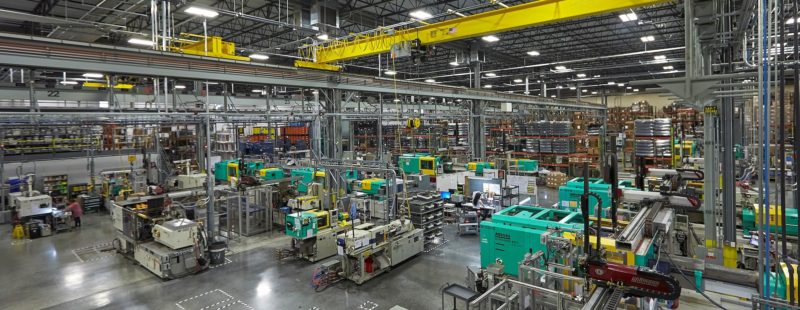
Hansen Plastics ESOP

HPC, a 100% ESOP owned company, celebrates its 50th anniversary next year, in 2021.

By the late 1980’s our kids were out of college and I began thinking about how we could smoothly exit from the plastic injection molding business. By this time I had joined an organization called TEC which was a support group of CEO/Owners. I heard many stories, plans and ideas on how my peers in the organization planned to execute a succession plan for their businesses. I came to the realization that the sale of a small business was easier “said than done.”

Essentially the potential buyers of a small business such as ours fell into 3 categories. Namely, Customers, Competitors, or Investors. None of them would be “cash” buyers, willing to pay a fair price for a going profitable enterprise. They all would want to pay a small down payment and give me, the owner, a 5 or more year “non-compete” contract to help earn or pay down all or part of the balance of the purchase price. The disadvantages of these types of transactions is that many of them end up as a merger or consolidation with the loss or displacement of many or all of our employees jobs. In other words no job security for the folks that helped build our company into a successful enterprise.

In 1988 or ’89 a fellow TEC member, named Bernie Siegel, mentioned that he thought our company would be a perfect candidate to sell via an Employee Stock Option Plan. In the same breath he handed me an invitation to an ESOP seminar to be presented by a firm named Menke and Associates. On half a whim, I decided to attend the seminar.

The ESOP presentation, by Menke, was delivered in a very knowledgeable and professional manner. The founder, John Menke, co-drafted the original ESOP legislation that allowed the implementation of ESOP plans. If an attendee brought 3 years of financials along they would evaluate your company for its suitability for an ESOP right on the spot. I returned home with a good first impression and thought about it for several months. I attended one more seminar along the way.

I will mention a few important pro and con features that were important to me.

  1. A very appealing feature to me was the deferral of Capital Gains Taxes on most of the
    transaction.
  2. Contributions to the ESOP trust were tax deductable.
  3. The sale could occur over several years if necessary.
  4. I could stay on with the company during the transition.
  5. The major “con” concern. The regulations required us to change the corporate form of the company from an “S” corporation to a “C” corporation. The “C” form had a much higher Federal Income Tax burden. If the ESOP didn’t work out we would have been “stuck” with higher tax “C” form for at least 5 years.

I figured out that the key management members of our company would have to “buy” into the plan early to make the ESOP a success. Most of their future retirement account contributions would shift from being invested in the current defined benefit plan to Company stock in the ESOP. So we had several small “key employee” meetings to explain and explore ESOP’s as I visualized installing one at HPC. The general reception was quite positive. I also spent quite a bit of time exploring local Chicago area ESOP consultants. I found Menke and Associates to offer the most knowledgeable, comprehensive and competitive firm to help us implement the ESOP plan. An additional “comfort” was added by our corporate attorney, Ray Dalton, who early on advised us that he could guide and lead us through the process, but he did not have the expertise to do a detailed plan. He also cautioned that we would not want to pay him to go through a learning curve to become an “expert ESOP consultant.”

My next task was to “test” the water and see if an ESOP “valuation” would produce a fair price for our company. ESOP regulations require a valuation must be made by an arm’s length consultant, not our own CPA firm. Menke referred us to a valuation consultant named Jack Scripps who agreed to come out to visit and do an Official ESOP valuation for $5,000.00. His report was quite extensive and came up with a valuation that I thought was “fair.” The next task was to find a bank that would make a “mirror loan” to the company with the company in turn loaning the funds to the ESOP trust, which could then write me a check for the number of shares I agreed to sell to the ESOP. I interviewed and eventually received quotes from three local banks.

The best proposal was presented by First American Bank of Dundee, IL. They had a young marketing/sales person, named Marty Carmody, who had been calling on us for 6 or 7 years, trying to secure our business. The bank, in addition to loaning us the money without a hitch, helped me select the rollover investments for the sale proceeds.

So, in 1991, three years after that first ESOP seminar I attended, we sold 30% of HPC’s corporate stock to the HPC employee stock option plan trust. It was a “big” day for the employees, the company and myself. We started contributing profits to the extent IRS regulations allowed to the plan trust and our employees over time became “owners.” Each and every one of them became owners of a part of the productive enterprise they worked for. And if the company was successful and increased in value, their piece of the pie also increased in value.

In 1994 we sold an additional 35% of HPC’s stock to the trust and in 1998, management secured the bank loan to buy the final 35% of the stock, making HPC a 100% ESOP owned company. I made my goal to exit smoothly and retire knowing that I had the satisfaction and privilege to have helped hand down ownership to the employees in the company they helped build.

When HPC celebrates its 50th anniversary next year, in 2021, we can conclude with pride that we together found a way to ensure the company’s continuity and growth. We all worked hard for it and the ESOP proved to be a truly WIN-WIN transaction.
Share this article:
LinkedIn
Twitter
Facebook
WhatsApp

Learn why an ESOP is better for You,
your Business, and your Employees

Upcoming Web Seminar

Free 90-Minute Webinar for Business Owners, CFOs & Advisors

Learn how ESOPs fuel growth, reduce taxes, and power succession—without giving up control.

Days
Hours
Minutes
Seconds

Why 2026 is the Time for ESOPs

Strong companies are using ESOPs to play offense. With rates stabilizing and talent still tight, employee ownership is delivering a durable edge:

    • Founder Liquidity—On Your Terms. Create a market for your shares without selling to private equity or competitors.
    • Major Tax Efficiency. Enable capital‑gains deferral for selling shareholders (Section 1042 eligibility) and reduce or even eliminate ongoing corporate income tax for S‑Corporation ESOPs—freeing cash for growth.
    • Talent Magnet. Meaningful employee ownership boosts engagement, retention, and performance—without relying solely on wage increases.
    • Resilient Margins. ESOP tax advantages help counter wage pressure, input costs, and tariffs—so more operating cash flows to strategy.
    • Control & Culture Intact. Transition ownership while keeping leadership and values in place.. Transition ownership while keeping leadership and values in place.

Bottom line: ESOPs create a rare win‑win‑win—for owners, the business, and employees.

What You’ll Learn

ESOP 101—Modern Playbook
How ESOPs work in 2026, who qualifies, deal structures, and timelines.

Tax Strategies that Change the Math
Capital‑gains deferral, corporate tax reduction/elimination for S‑Corp ESOPs, deductible contributions, and cash‑flow modeling.

Talent & Culture
Retention without across‑the‑board raises; ownership communications that actually move the needle.

Protecting Margins
How ESOP incentives can offset cost inflation and support reinvestment.

Valuation & Financing in Today’s Market
Bank/seller notes, mezzanine options, rate considerations, and why “bankable ESOPs” are closing now.

Governance & Control
Board, trustee, and management roles—what really changes (and what doesn’t).

Who Should Attend

    • Business Owners planning an exit, partial sale, or recapitalization

    • CFOs evaluating capital structure and tax strategy

    • Advisors & Succession Planners guiding owner‑led companies

    • HR & ESOP Committee Members building engagement around ownership

Agenda (90 Minutes)

    1. Welcome, Speakers & Why ESOPs in 2026 (5 min)
      Quick orientation; who Menke is and why ESOPs are winning right now.
    2. ESOP Basics & Business Owner Benefits (10 min)
      What an ESOP is; liquidity, diversification, succession, productivity.
    3. Myth‑Busting: What ESOPs Do—and Don’t—Require (5 min)
      No, you don’t have to sell 30%+, borrow big, or give up control.
    4. Deal Structures & Transaction Paths (10 min)
      Cash‑contribution (pay‑as‑you‑go), leveraged (bank/seller notes), and stock contribution; when each fits.
    5. Typical Scenarios & Outcomes (10 min)
      Gradual sales, minority/majority sales, 100% buyouts, and recap strategies.
    6. Who’s a Strong Fit (and Common Constraints) (5 min)
      Profitability, team/transition readiness, industry notes.
    7. Tax Strategy Deep Dive (10 min)
      S‑Corp ESOP distribution savings; C‑Corp §1042 capital‑gains deferral; entity‑path options.
    8. Valuation & Pricing vs. Third‑Party Sales (8 min)
      FMV standards, control vs. minority value, practical comparisons.
    9. Financing the ESOP (8 min)
      Bank market overview, seller paper, balance‑sheet effects, cash‑flow modeling.
    10. Plan Operations & Employee Communications (8 min)
      Eligibility, vesting, distributions, disclosures, and how transparency drives results.
    11. Culture, Engagement & Measured Performance Uplift (6 min)
      What changes on day 2; tying ownership to productivity.
    12. Roadmap & Next Steps (3 min)
      Feasibility, design/adopt, contributions, and timing the sale.
    13. Live Q&A (2 min)

Hear From Past Attendees

“I came in skeptical. I left with a concrete roadmap and the math to brief our board.”

“This clarified our exit plan and showed how we can reward employees at the same time."

Your Presenter: Phil DeDominicis

Phil DeDominicis is an ESOP strategist and M&A advisor who has guided 300+ companies through ESOP formations, financing, and transactions over 20+ years at Menke & Associates. He specializes in selling ESOP‑owned businesses to financial or strategic buyers and in helping ESOP companies acquire other businesses.
Before Menke, Phil spent 14 years in investment banking M&A at Morgan Stanley and Salomon Smith Barney, advising middle‑market companies on change‑of‑control transactions. He holds a B.S. in Chemical Engineering from the University of Delaware (1985) and an MBA in Finance & Accounting from UCLA Anderson (1989). Phil currently serves on six for‑profit and not‑for‑profit boards.

What Phil will cover:

    • Where ESOPs win in 2026 (tax, talent, and control)
    • Owner liquidity paths: minority, majority, and 100% sales
    • Financing options and what lenders look for
    • Valuation reality vs. third‑party sales
    • How to prep a board, trustee, and employees for a successful close

Reserve Your Spot Now

Seats are limited. Save yours now and receive the ESOP Feasibility Checklist.

10:00AM – 11:30AM PT
11:00AM – 12:30PM MT
12:00PM – 1:30PM CT
1:00PM – 2:30PM ET

No cost. Suitable for companies with $5M–$500M+ in revenue across construction, manufacturing, services, distribution, tech, and more.

FAQ (Quick Hits)

    • Do I lose control? No—most ESOPs preserve day‑to‑day control with your leadership team and board.

    • Is this only for certain industries? ESOPs work across sectors when cash flow is stable and leadership continuity matters.

    • Can we do a partial sale? Yes—stage liquidity over time while capturing tax benefits.

READY FOR AN ESOP NOW?

Interested in finding out how an ESOP could work for your company?

For a free preliminary analysis, just fill out our ESOP Feasibility Questionnaire.

Related Articles

Man viewing employee stock ownership plan presentation on computer screen.
July 29, 2026
Don’t miss this opportunity to discover how ESOPs can align your business goals with the needs of employees and stakeholders.
Brass straightedge on slate, representing consistent ESOP valuation standards under new federal law
September 17, 2026
For fifty years, the hardest question in employee ownership was not how to finance the deal or how to structure the tax benefits. It was what “adequate consideration” actually meant. Congress has now answered it — and the answer is narrower, and more useful, than the headlines suggest.
Unfinished steel-frame building with a focused beam of light, representing AEC marketing and ideal client focus
September 14, 2026
Most contractors say they win work on relationships, and most are right, up to a point. What happens when the people who hold those relationships retire, or when the firm tries to grow into a market where nobody knows its name?
Abstract suspended architectural span under cable tension, representing the long-term structure of a Section 1042 tax deferral
August 31, 2026
A seller who elects Section 1042 on a $100 million ESOP transaction can defer roughly $33 million in capital gains tax, potentially for life. The same election, structured without care, can leave that seller carrying leverage on a securities portfolio for decades. The difference is in how the portfolio is built.
Abstract network of interconnected nodes representing ESOP employee ownership culture
August 17, 2026
Two companies can have identical ESOP structures on paper and produce completely different results. The difference usually comes down to three specific things — and most companies get at least one of them wrong.
Abstract image of a converging path symbolizing a 2026 ESOP market midyear review
August 3, 2026
Halfway through 2026, the ESOP market looks different than it did in January — bank lending is more competitive, private equity firms are eyeing ESOPs as an exit, and legislation is moving. Here’s what’s actually changed.